 Quick Answer: Abridged accounts are still available to eligible UK small companies, but not for much longer. Under the current rules, qualifying companies can prepare abridged accounts with the agreement of all members. However, Companies House has confirmed that this option will be removed from 1 April 2028, when new accounts filing requirements take effect.
If you’ve been researching UK company accounts for more than ten minutes, you’ve probably come across the phrase “abridged accounts.” Then you visit another website and suddenly everyone is talking about filleted accounts instead.
So which one is correct?
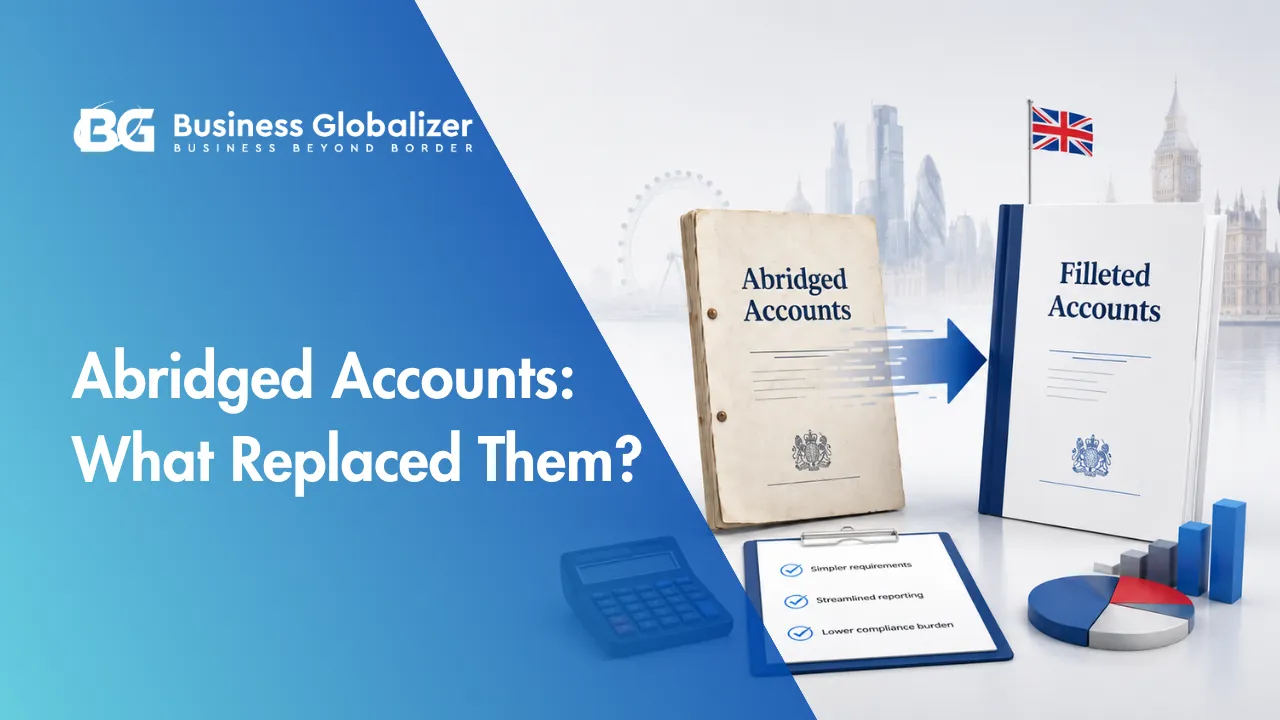
Actually…both are, depending on when the information was written. Abridged accounts are still part of the UK reporting system, but their days are numbered. Companies House has confirmed that the option will disappear in April 2028. Until then, eligible companies can still use it, while filleted accounts remain another reporting option.
If you’re planning for UK company formation or already running one, knowing the difference matters. Let’s clear up what you can file today and what’s about to change.
What Are Abridged Accounts?
Abridged accounts are simplified statutory or annual accounts that qualifying UK small companies can prepare under the Companies Act reporting framework.
They contain less financial detail than full accounts, with certain balance sheet and profit and loss items presented in a shortened form. But there’s an important condition: all company members must agree to the abridged accounts for the relevant accounting period.
And yes, directors are still responsible for preparing accurate accounts. Less detail doesn’t mean fewer legal responsibilities.
Do Abridged Accounts Still Exist?
Yes, they do. But that is changing.
As of October 2026, eligible UK small companies can still prepare and file abridged accounts, provided they meet the requirements and all members agree.
However, Companies House has confirmed that abridged accounts will be removed from 1 April 2028 under the Economic Crime and Corporate Transparency Act reforms. From that date, small companies will face revised filing requirements, including submitting a profit and loss account to Companies House.
So if you’re filing today, abridged accounts may still be an option. If you’re preparing for 2028, you’ll need to plan around the new rules.
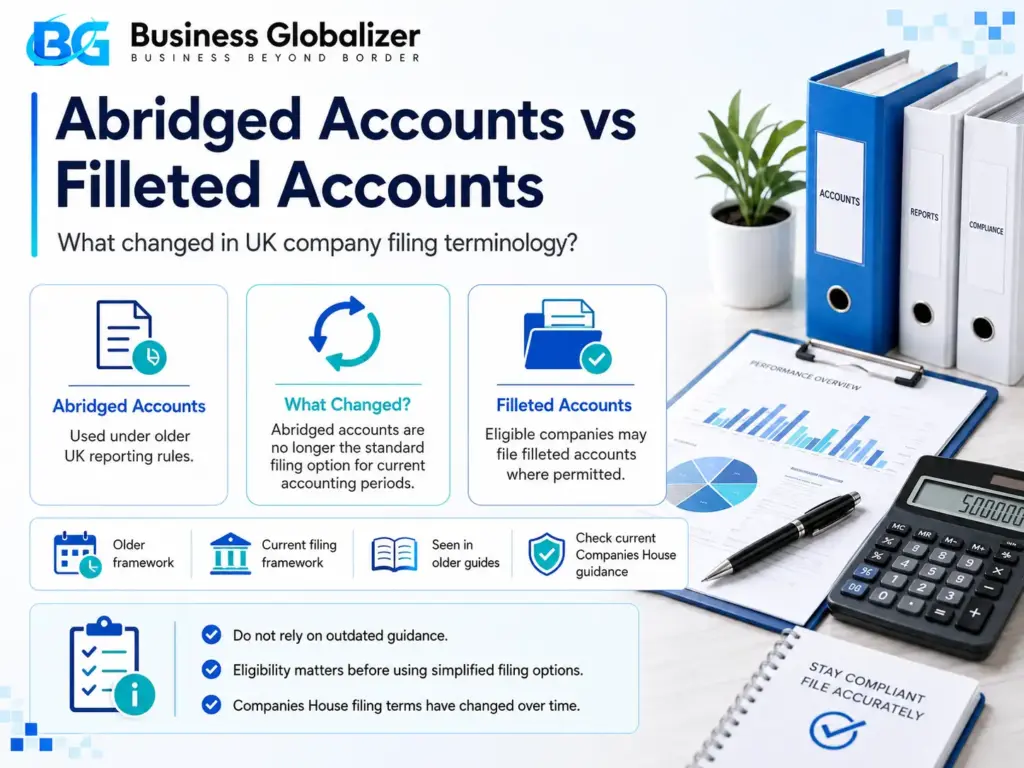
Abridged Accounts vs Filleted Accounts
Both options can reduce the financial information made publicly available, but they work differently. Abridged accounts simplify certain figures within the accounts themselves, while filleted accounts allow eligible companies to leave out certain documents when filing with Companies House.
| Abridged Accounts | Filleted Accounts |
| Simplify certain balance sheet or profit and loss figures. | Omit certain information from the publicly filed accounts. |
| Require agreement from all company members for the accounting period. | Depend on the company’s eligibility for the relevant filing exemptions. |
| Still available to qualifying companies until the 2028 reforms take effect. | Available under the current filing rules, subject to eligibility. |
| The option will be removed from 1 April 2028. | The filing framework will also change from April 2028. |
The important difference? Abridged accounts change how certain figures are presented. Filleted accounts change what eligible companies submit to the public register.
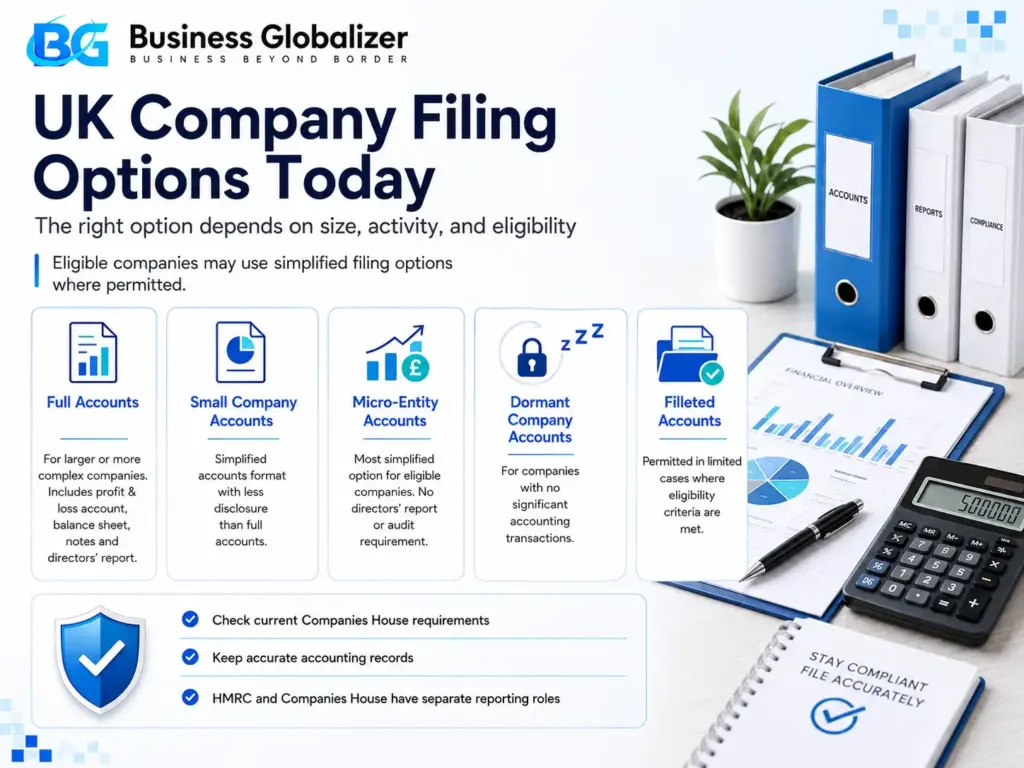
What Can UK Companies File Today?
The right accounts depend on your company’s size, activity, and eligibility. Under the current Companies House framework, the options include:
- Full accounts for companies that must prepare and file more detailed financial statements.
- Small company accounts for businesses meeting the relevant size and eligibility requirements.
- Micro-entity accounts for qualifying very small companies.
- Dormant company accounts for companies meeting the applicable dormancy rules.
- Abridged accounts for eligible small companies, with all members’ agreement.
- Filleted accounts where the relevant filing exemptions apply.
One thing worth remembering: these aren’t all completely separate categories. For example, an eligible small company may prepare abridged accounts and use permitted filing exemptions.
The right choice depends on what your company qualifies for, not simply which option involves the least paperwork.
What Changes for UK Company Accounts in April 2028?
Here’s the date UK company directors should remember: 1 April 2028.
Companies House has confirmed several changes to annual accounts filing under the Economic Crime and Corporate Transparency Act reforms.
The main changes include:
- Abridged accounts will no longer be available.
- Small companies and micro-entities will need to file profit and loss accounts.
- Eligible companies will have the option to keep their filed profit and loss information off the public register.
- Annual accounts must be filed using commercial software.
- Companies claiming audit exemptions will face strengthened eligibility statement requirements.
So while abridged accounts are still available today, companies should start preparing for the new filing system well before April 2028.
Why Do So Many People Still Search for Abridged Accounts?
Because thousands of older guides, blogs, videos, and accounting resources still use the term. If a director formed a company several years ago, their accountant may also have used “abridged accounts” at the time.
And there’s another reason people still search for the term: abridged accounts remain a valid option for qualifying companies until the new rules take effect. The confusion comes from older explanations, newer reform announcements, and filing options that sound surprisingly similar.
Common Mistakes to Avoid
The biggest mistakes usually happen because people rely on outdated information. A few practical reminders:
- Don’t assume abridged accounts have already been abolished.
- Check whether your company qualifies before choosing abridged or filleted accounts.
- Remember that abridged accounts require agreement from all company members.
- Don’t confuse preparing abridged accounts with filing filleted accounts.
- Keep accurate accounting records, regardless of which accounts you file.
- Prepare for the new Companies House filing requirements taking effect in April 2028.
Business Globalizer: Helping You File the Right Accounts
UK reporting requirements change over time, and older accounting terms don’t always disappear overnight.
At Business Globalizer, we help founders understand which filing option actually applies today. Whether your UK company needs a registered office address, corporate taxation, annual accounts, micro-entity accounts, dormant company accounts, confirmation statements, or broader compliance support, we help you file accurately and on time. We also help with company dissolution and company restoration whenever required.
Closing Thoughts
Abridged accounts aren’t gone yet, but the rules are changing.
For now, qualifying UK companies can still use them, provided the legal requirements are met. From April 2028, however, companies will need to follow the revised Companies House filing framework.
So before choosing between abridged, filleted, or other accounts, check what your company actually qualifies for and what the current rules require.
Because filing the right accounts isn’t just about keeping paperwork short. It’s about getting the reporting right, today and when the rules change.
Key Insights
- Abridged accounts are still available to eligible UK small companies in 2026.
- All company members must agree before abridged accounts can be prepared.
- Abridged accounts simplify certain financial figures, while filleted accounts reduce what is publicly filed.
- Companies House will remove the abridged accounts option from 1 April 2028.
- Small companies and micro-entities will face new profit and loss account filing requirements from April 2028.
- Commercial software will become mandatory for Companies House accounts filing from April 2028.
- The right accounts depend on company size, eligibility, and reporting requirements.
- Companies House accounts and HMRC Corporation Tax reporting remain separate obligations.
- Dormant companies must still meet their applicable annual accounts filing requirements.
- Checking current filing rules helps directors avoid mistakes and prepare for upcoming changes.
FAQ’s on Abridged Accounts
What are abridged accounts?
Abridged accounts are simplified statutory accounts that eligible UK small companies can prepare with less detail in certain financial statements. All company members must agree to their preparation for the relevant accounting period.
Do abridged accounts still exist?
Yes. As of October 2026, qualifying UK small companies can still prepare and file abridged accounts. However, Companies House has confirmed that this option will be removed from 1 April 2028.
Are abridged accounts the same as filleted accounts?
No. Abridged accounts simplify certain figures in the accounts themselves. Filleted accounts allow eligible companies to leave out certain information when filing with Companies House. They serve different purposes, even though both can reduce publicly available financial details.
Why do older websites still mention abridged accounts?
Answer: Many articles were written before the reporting changes took effect and have never been updated. Always check whether the guidance reflects the current Companies House rules.
Who can file filleted accounts?
Eligible small companies can use permitted filing exemptions to omit certain information from their Companies House accounts. The exact options depend on the company’s reporting status and applicable legal requirements.
Do abridged accounts affect Corporation Tax?
Answer: No. Corporation Tax obligations are separate from whether a company previously prepared abridged accounts or now files under the current reporting framework.
When will abridged accounts be abolished in the UK?
Companies House has confirmed that the abridged accounts option will be removed from 1 April 2028. The changes also introduce new profit and loss account filing requirements for small companies and micro-entities, along with mandatory commercial software filing.